
Your Local Mortgage Lender
Located in Annapolis, Maryland
Personalized Mortgage Experience
Chris Nieberlein offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Annapolis, Maryland.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
How a Westminster Mortgage Lender Simplifies Construction Loans
Streamlining Your Path to a Custom Home in Maryland
Building a custom home in Westminster, MD, is a dream for many, but navigating the financing process can often feel overwhelming. Unlike traditional mortgages designed for existing homes, funding for a new build requires specialized capital that is disbursed in stages as construction progresses. This is where partnering with an experienced local expert becomes invaluable. Chris Nieberlein at Bay Capital Mortgage is dedicated to simplifying construction loans, transforming a complex financial journey into a smooth path to your dream home.
With years of experience and a client-focused approach, Bay Capital Mortgage offers tailored solutions designed to make your custom build financially straightforward. By understanding the unique challenges of the local Carroll County market, Chris provides the expert guidance necessary to ensure your project stays on track and within budget.
Key Benefits of Construction-to-Permanent Loans
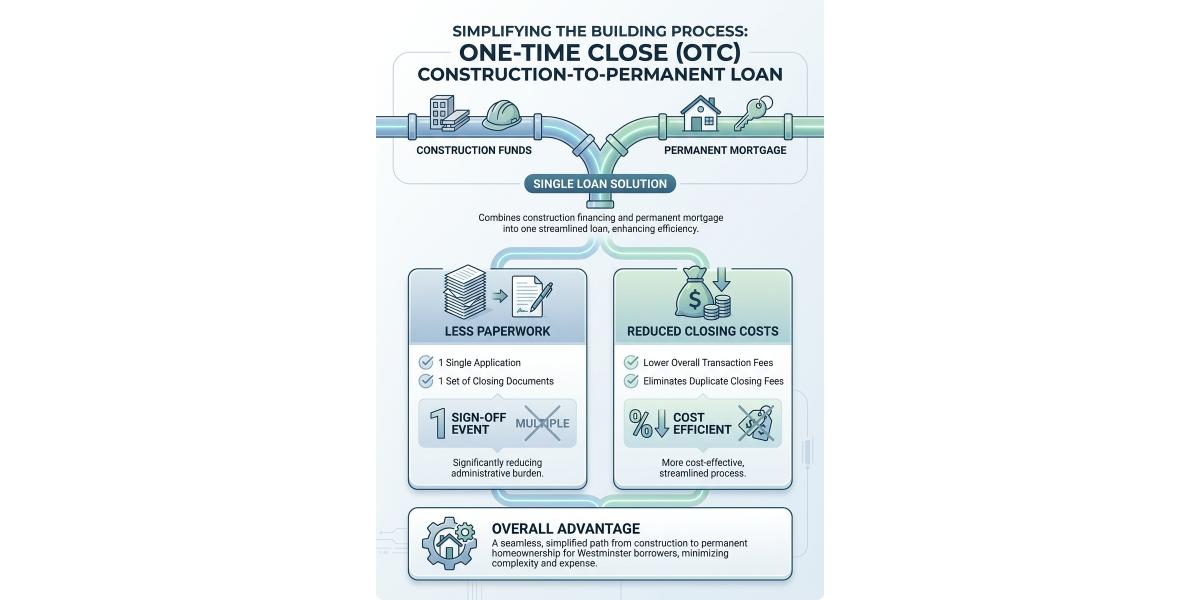
One of the most significant ways a Westminster mortgage lender simplifies the building process is through the One-Time Close (OTC) Construction-to-Permanent Loan. This innovative financing solution combines the construction funds and your permanent mortgage into a single loan. This approach offers several distinct advantages:
Less Paperwork: You only need to complete one application and sign one set of closing documents, significantly reducing the administrative burden.
Reduced Closing Costs: Because you are only closing on a single loan, you save money by avoiding the duplicate fees associated with securing two separate loans.
Interest-Only Payments: During the construction phase, borrowers typically make only interest payments on the funds that have been disbursed. This helps manage cash flow and eases monthly financial commitments while your home is being built.
Interest Rate Protection: Market fluctuations are a common concern during a long build. Many lenders allow you to lock in an interest rate at the time of your loan approval. In some cases, a float down option is available if market rates drop significantly before your home is complete.
By utilizing progressive disbursements, or draws, funds are released directly to your builder only as specific milestones are met and verified. This structured oversight provides peace of mind that your capital is being managed efficiently.

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Our Location
Social Media Links
YouTube

Copyright 2026. All rights reserved. Chris Nieberlein NMLS #313519 | Bay Capital Mortgage Corp. NMLS #39610 | Equal Housing Opportunity | Equal Housing Lender
Copyright 2026. All rights reserved. Chris Nieberlein NMLS #313519 | Bay Capital Mortgage Corp. NMLS #39610 | Equal Housing Opportunity | Equal Housing Lender