How much house can you afford in Carroll County, MD? Start with the monthly payment
Determining how much house you can afford in Carroll County, MD starts with finding a monthly payment that feels sustainable for your budget. The price of a home is only one piece. What matters day to day is the full cost of owning it, and a few steps can bring that into focus before you start touring.
Budgeting for How Much House You Can Afford in Carroll County MD
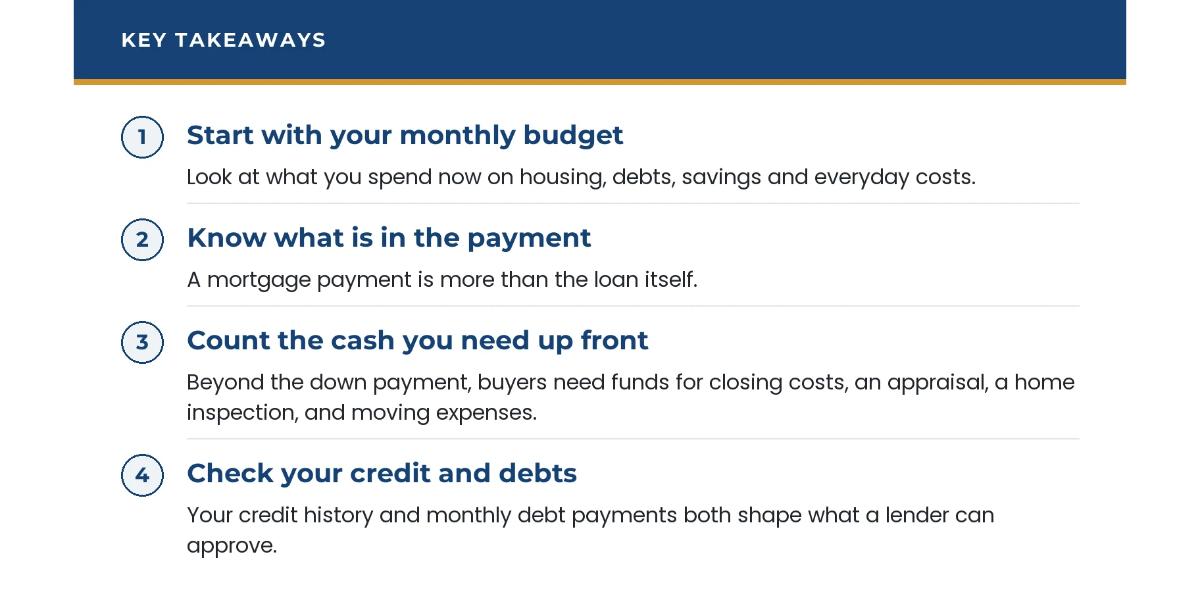
Look at what you spend now on housing, debts, savings and everyday costs. Then decide how much of your income you want to commit to a house payment. A lender will look at income against debts when approving a loan, but your own comfort level is just as important. A payment that fits on paper can still feel tight if it leaves no room for savings.
Know what is in the payment
A mortgage payment is more than the loan itself. It typically includes principal and interest, property taxes, and homeowners insurance. Depending on the loan and down payment, mortgage insurance may be added as well. Some homes also have HOA dues or well and septic upkeep to plan for, which is common in more rural parts of the county.
Property taxes and insurance differ from one home to the next, so ask your agent for estimates on any house you are seriously considering.
Count the cash you need up front
Beyond the down payment, buyers need funds for closing costs, an appraisal, a home inspection, and moving expenses. Lenders also look at whether you have some savings left after closing. Planning for these early keeps surprises to a minimum. Different loan programs ask for different down payments, so it helps to compare them rather than assume one number.
Check your credit and debts
Your credit history and monthly debt payments both shape what a lender can approve. Pulling your credit report ahead of time lets you correct errors and see where you stand. Paying down a high-balance card or avoiding new debt before you apply can make a difference in the file.
Compare loan types
Conventional, FHA, VA and USDA loans are all options for buyers in this area, and each handles down payment, credit and mortgage insurance differently. Some also depend on the property location, so eligibility should be checked address by address rather than assumed. A loan officer can show how the same home might look under more than one program.
Get a pre-approval to turn estimates into numbers
Online calculators are a decent starting point, but they use general assumptions. A pre-approval uses your actual income, assets and credit, so the price range you see reflects your situation. From there you and your agent can focus on homes that fit the payment you chose.
Talk it through with a local lender
Chris Nieberlein is a correspondent lender with Bay Capital Mortgage serving buyers in Westminster and throughout Carroll County. He can walk you through the monthly payment, the cash needed to close, and the loan options that fit. Call (410) 913-1530 or visit chrisnieberlein.com to discover how much house you can afford in Carroll County, MD today. Chris Nieberlein, NMLS 313519. Bay Capital Mortgage Corp., NMLS 39610. All loans subject to credit approval and underwriting. Equal Housing Opportunity | Equal Housing Lender.


